The arithmetic looks settled. The card charges interest, savings earn next to nothing, so every spare pound belongs against the balance. Then the car needs a part, the card is the only thing to hand, and the balance sits exactly where it did back in March. This has already happened once or twice, which is usually the sign that the obvious answer has something missing from it.
The quick answer
The honest framing is not “save or repay” at all. One thing settles it: whether an ordinary emergency would land straight back on the card. Where it would, repayments are not shrinking the balance at all but financing the next repair, and the interest saved barely registers beside the cycle. Sizing a buffer against your own likely surprises takes minutes, and the number is smaller than most people assume.
Coming up: the thing that decides this, a table you can find your own pattern in, and why the buffer is far smaller than most advice implies.
The choice was never saving against repaying
Each position holds up on paper. One treats interest as the enemy and sends every spare pound at the balance, which is arithmetically correct taken alone. The other points out that a household with no cushion sits one boiler away from borrowing again, which is what actually happens in practice. The disagreement persists because each side is right about a completely different failure.
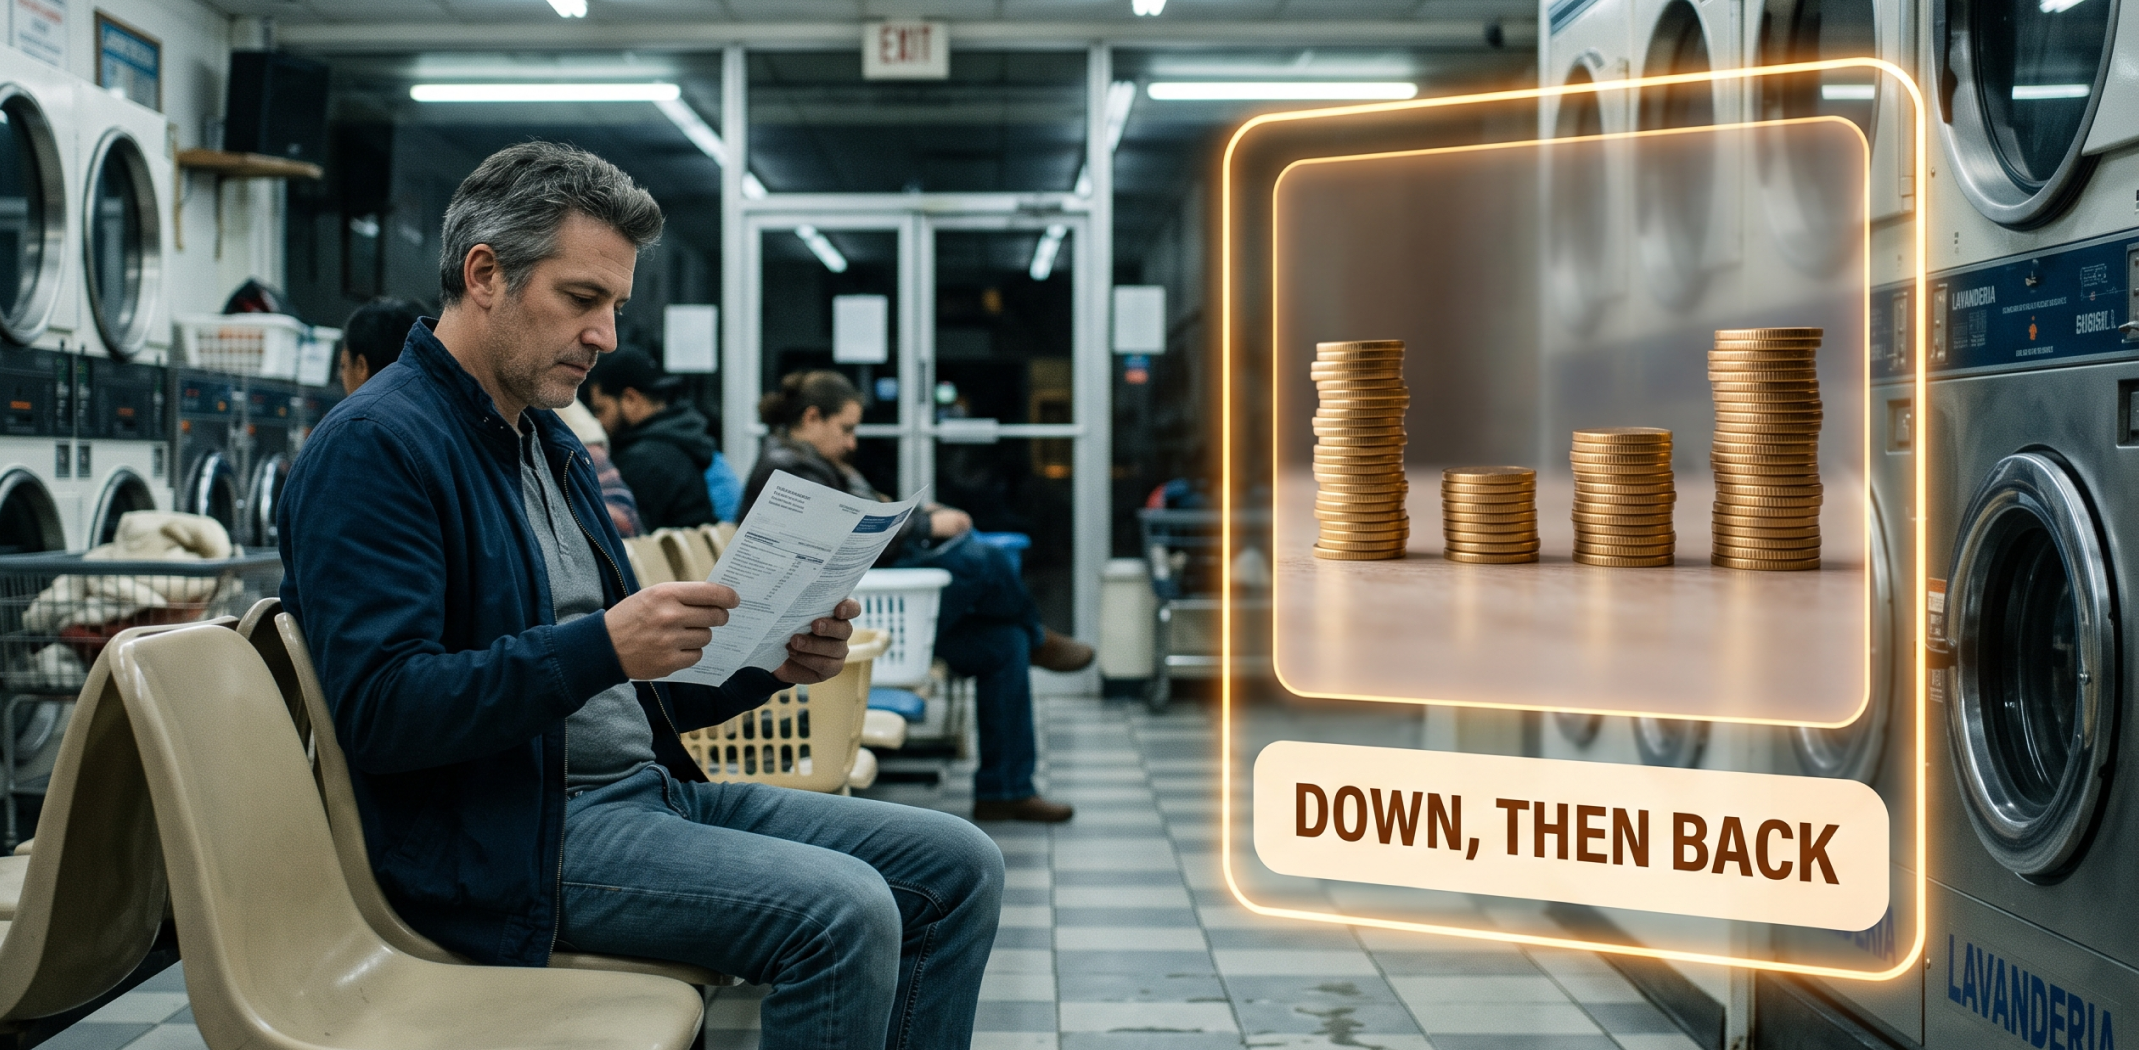
The mechanism deserves seeing plainly. Additional repayments only shrink a balance while nothing pushes it upward again. Without a cushion, an everyday surprise goes on the card by default, meaning three months of effort quietly paid for a repair instead of the debt. A small cushion breaks that loop, and checking whether your own balance keeps refilling usually settles the argument faster than any interest calculation.
Which means the question was never which approach is mathematically superior. It is whether your repayments are sticking at all, and that answer sits in your own statements.
Find your own pattern in the table
Look at the past twelve months instead of the interest rate: how often an unplanned cost ended up on credit. Then locate yourself in the table below. Sorting that honestly takes a few minutes and usually decides the order.
| Your pattern | What usually works | Why |
|---|---|---|
| The balance keeps climbing back | Small cushion first, then attack it | Repayments are financing repairs rather than the debt |
| Balance falls steadily | Keep repaying, buffer alongside | The cycle is already broken, so speed wins |
| Very high rate, nothing has broken | Split it, with a smaller cushion | The rate matters far more when nothing interrupts |
| No idea how often it happens | Check twelve months of statements | Every row above depends on it |
Take those as a starting point, not a rule. The interest rate, whether any of the debt risks escalating, the age of your car and boiler and whether anybody else could help in an emergency all move the line, which is exactly why the answer belongs to your situation.
How small the cushion genuinely needs to be
This is the part most people miss: the cushion that ends the cycle is nothing like three months of expenses. That figure belongs to job loss, an entirely separate problem. What stops a card refilling is enough to cover the sort of thing that has actually happened to you, and pricing your own likely surprises usually lands somewhere between two hundred and a thousand.
Three things set the size, and not one of them is a standard rule.
What decides your own figure
Whatever actually broke last time. Not the worst case at all. The everyday one: a tyre, a tooth, a boiler part, an excess. Work from what genuinely happened rather than what conceivably might.
What you cannot delay. Some surprises can wait a fortnight and some cannot. The buffer only has to cover the ones that would otherwise go on credit within days.
How quickly you could refill it. A cushion you can rebuild inside six weeks is allowed to be smaller than one you could not. That is precisely why an identical figure suits one household and fails another.
Three inputs, a single figure, and it comes out well below three months of anything.
Notice that this does not mean pausing repayments for a year. For most households the buffer takes weeks rather than months, and a roadmap with a target and a date exists so the pause is short and deliberate rather than open-ended.
The real price of repaying and nothing else
It costs the progress itself. Three years of disciplined overpayment, interrupted twice by a car and once by a dentist, can leave a balance sitting almost precisely where it began, and the person concludes they are hopeless with money when in fact the plan had no protection against ordinary life.
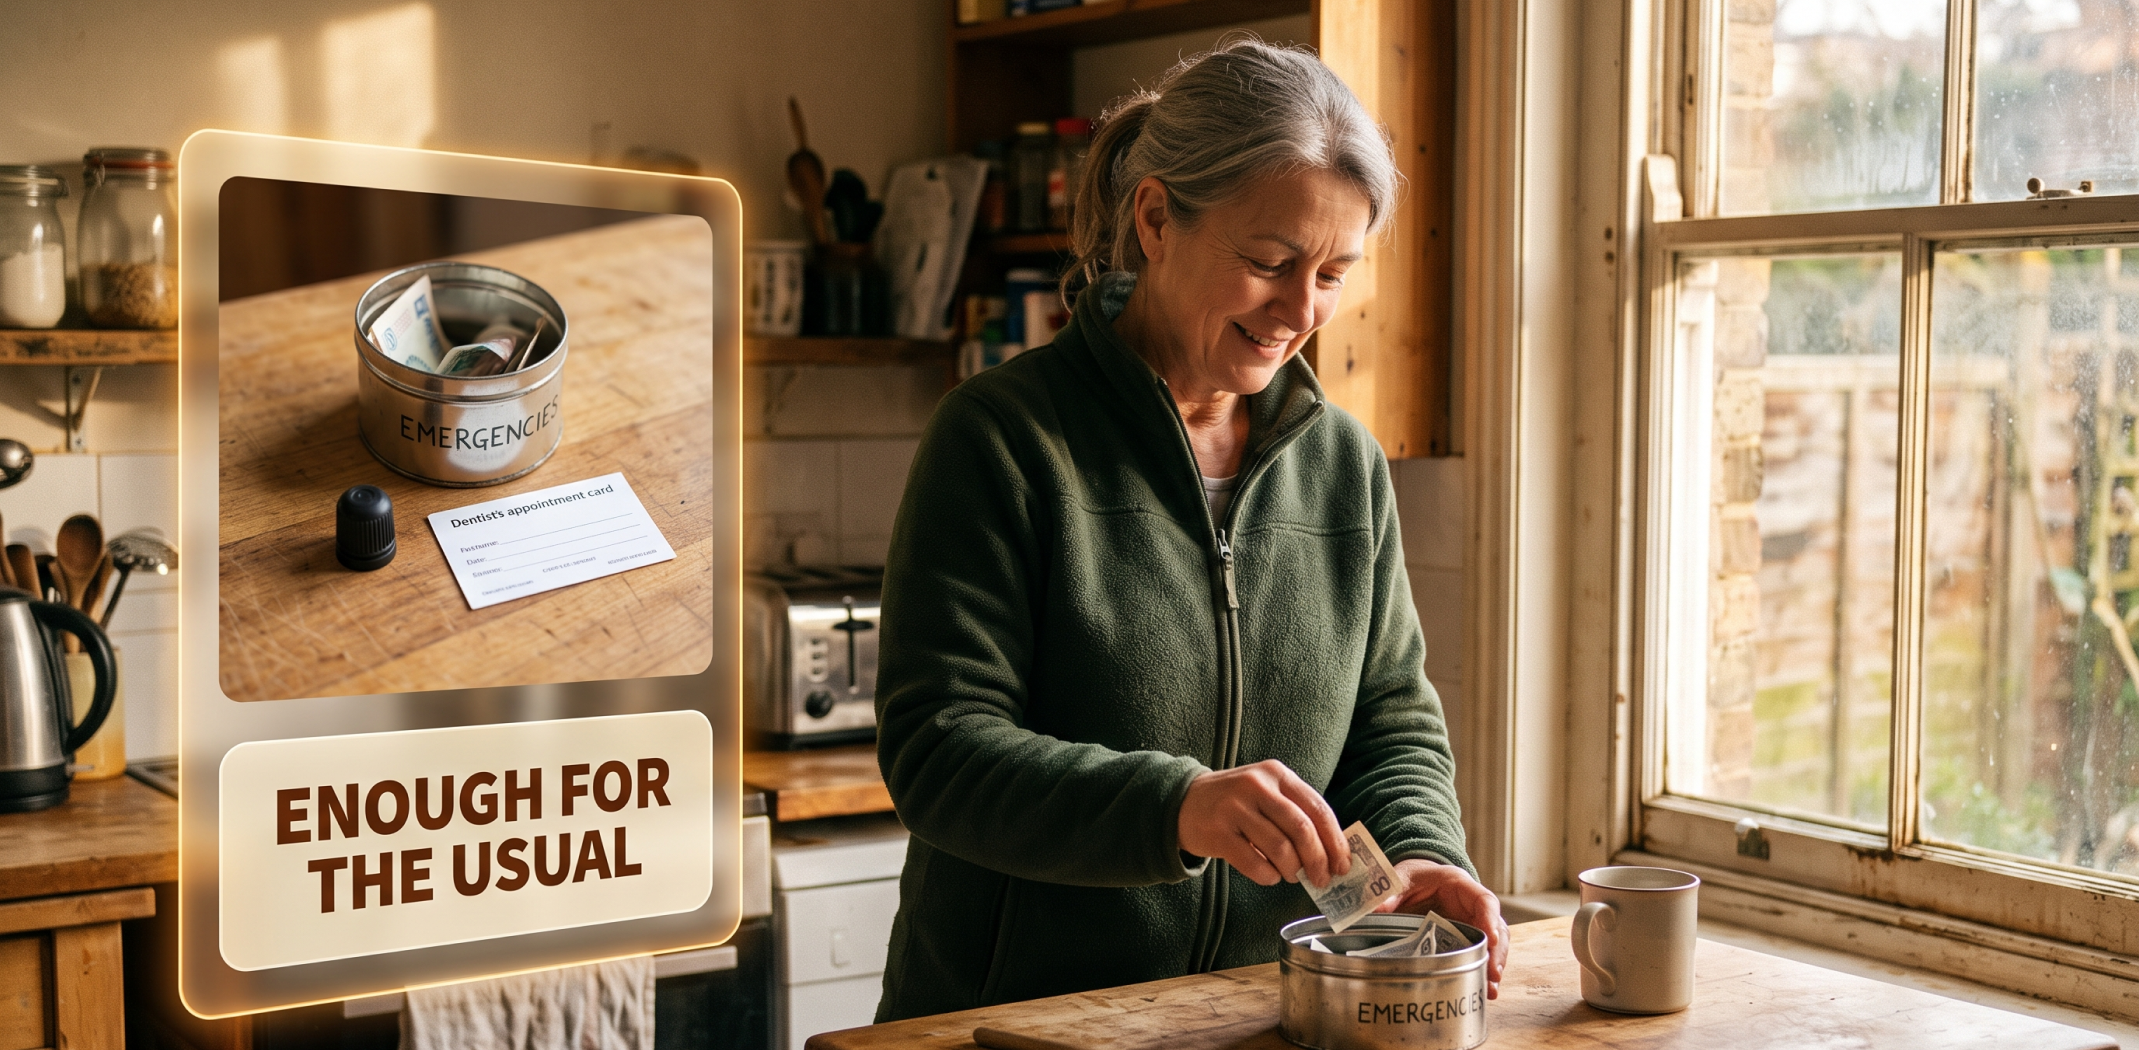
A second cost matters more than the money does. Each time the balance climbs back, the effort stops feeling worth making, and plans get abandoned on discouragement long before they fail on arithmetic. A buffer sized to your own surprises is what keeps the effort visible, which is what keeps it going.
Repaying hard vs saving hard vs sequencing it
You can work this out yourself, for free, with a year of statements and an hour. Here is how the usual approaches compare with ordering the two deliberately.
| Way to decide | Cost | Built on your own year? | Time |
|---|---|---|---|
| Everything at the debt | Free | No – ignores the refill cycle | Years, often reset |
| Save first, ignore the rate | Free | No – expensive debt keeps running | Slow on both |
| A debt advice service | Free to low | Sometimes – excellent for serious debt | Weeks |
| $500 Emergency Fund Roadmap | $14 | Yes – your surprises, your number, your order | About 15 min |
“Is sitting on cash while paying interest not simply a loss?” On arithmetic alone it is, and the objection is correct as far as it travels. The reason it still loses in practice is that it assumes nothing interrupts the plan, and the whole point of an emergency fund is that something always does. A small buffer costs a little interest and protects three years of repayments, which is usually the better trade. If the debt is at serious risk of escalating, or you are already behind on payments, that is a different situation and free debt advice services are the right first call rather than any planning tool. This is general educational guidance rather than financial advice.
If that still sounds like a detour, two people carried an identical balance and only one of them cleared it.
Two people, one identical balance
One of them repaid hard for three years and ended up roughly where she began. The other paused for six weeks before starting.
“Three years of overpaying and the balance was almost identical, because every time it dropped something broke. Six weeks of building four hundred first, and this is the first year it has actually gone down.”
Marguerite B. · care assistant, Tucson AZ
“My rate was high and nothing had gone wrong in a year, so the buffer stayed small and most of it went at the card. Different situation, different order, and the numbers said so rather than a rule.”
Cormac D. · warehouse picker, Youngstown OH
Once the order is set, the month has to hold it, and the Personal Budget Builder is built for that part. Results vary; this is general guidance rather than financial advice.
Five short answers, and your own figure lands the same day, worked from the sort of surprise that has genuinely happened to you rather than from a standard three-month rule. It sets the sequence as well: how long the cushion takes to build, when repayments start again and what the whole detour costs in interest. For most households the pause runs to weeks rather than months, and it is the final time the balance climbs back.
*Individual results may vary.