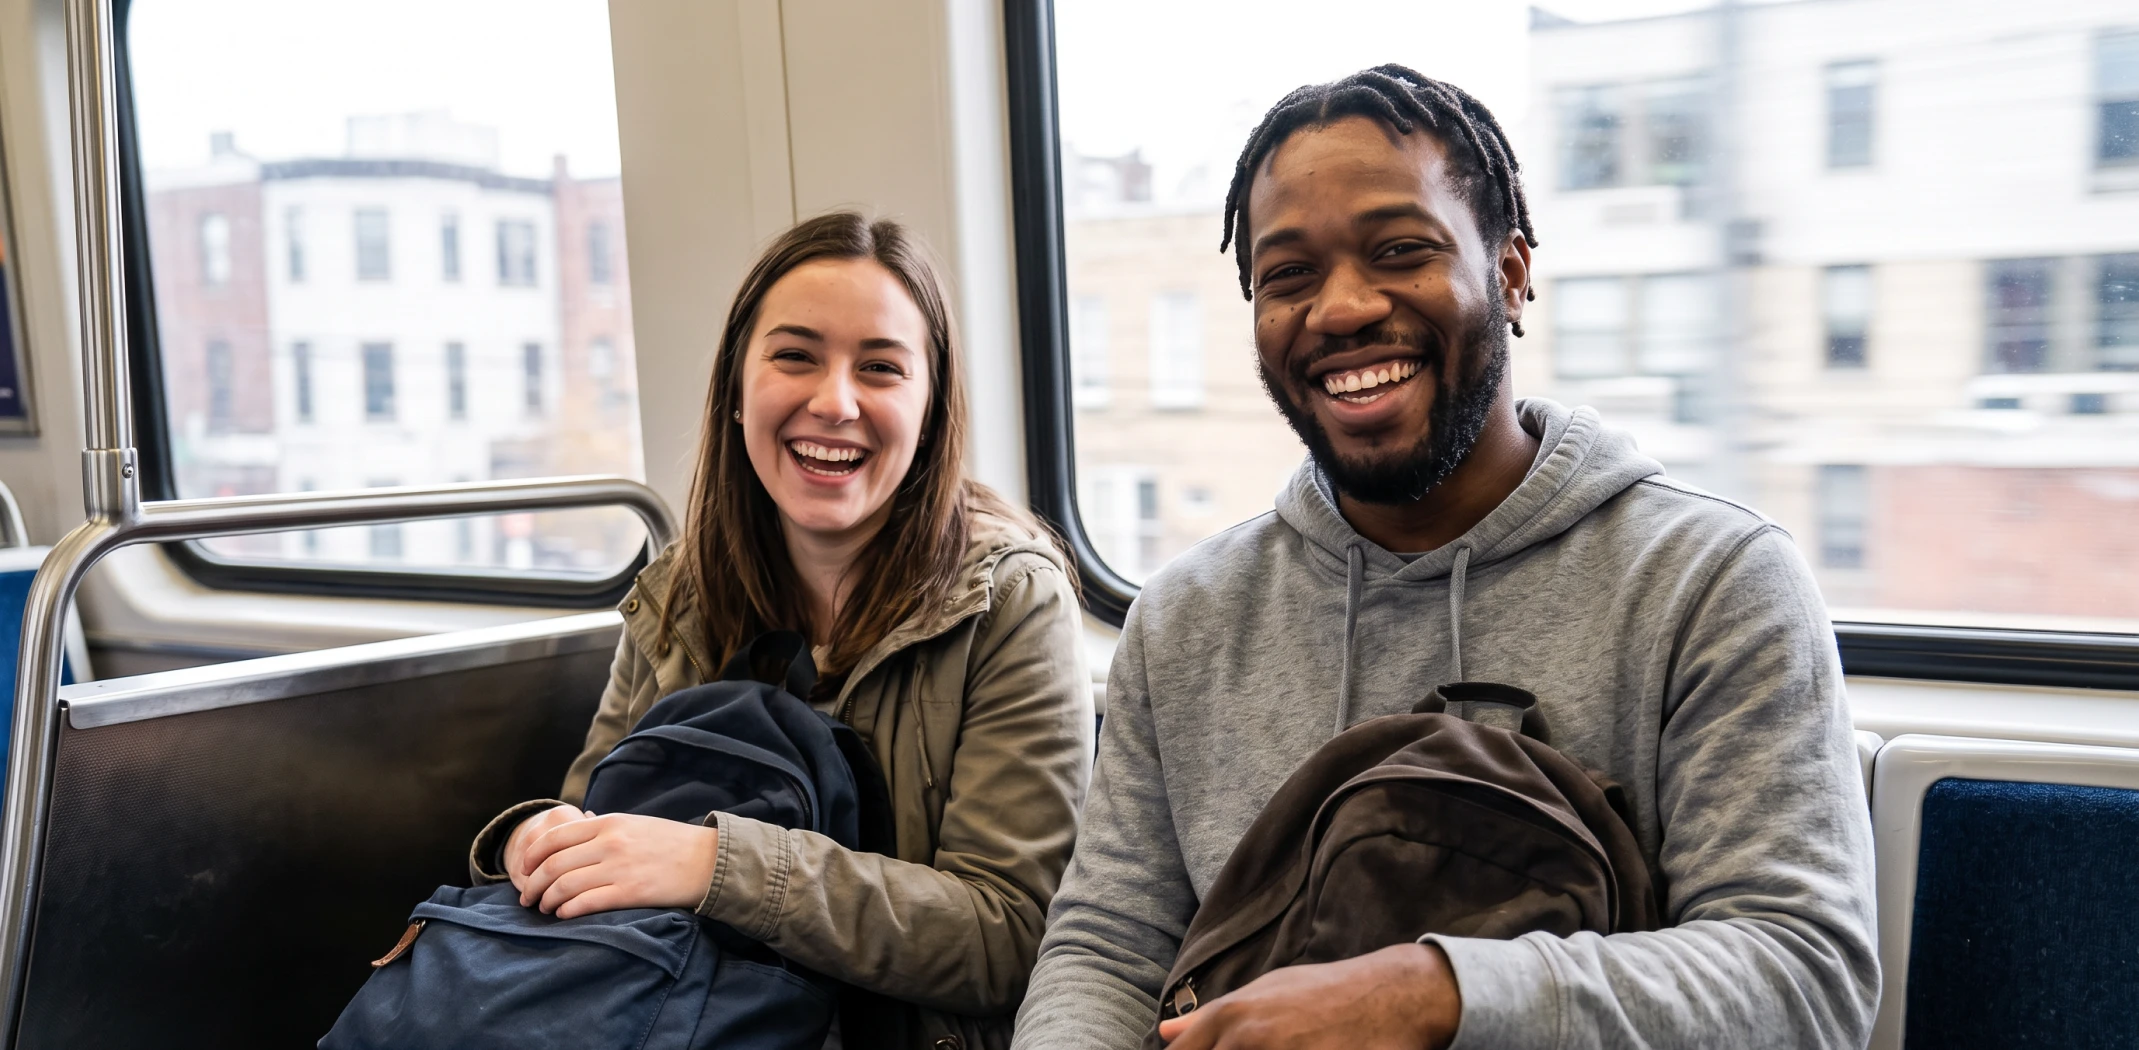
Saving challenges looked easy to Andy the first time. A dollar in week one, two in week two, and a nice total at the end. He is a 27-year-old line cook in Louisville, Kentucky, and he lasted until week 14. The weekly amounts kept climbing, the holidays were close, and after one missed week he felt it was over.
He tried again because he had to. His car had died the winter before. Two buses took 75 minutes each way, and after late shifts he paid for rides because the last bus was gone. A reliable used car would cost about $3,000.
His first challenge failed for a simple reason. It was built for a year that was not his, and it said nothing about bad weeks.
Why the classic challenge breaks in winter
The well-known version adds a dollar every week. That means the biggest weeks land in November and December, right when gifts, travel and heating bills arrive. Most people never reach them. A challenge that matches your own income and your own costly months has a much better chance.
So the second time, Andy did not print a chart from the internet. He set up a savings challenge built from his own weekly amount and busy months.
Setting up a challenge that knows his year
Ten questions came first. A weekly amount that would not hurt: $50. The goal: a car. Expensive months: December. A separate account: not yet, but he would open one. Biggest risk: surprise bills. Motivation: 8 of 10. And yes to reminders and to a friend who would see his progress.
His challenge, explained
the same $50 each week gives $2,600. Growing weeks push the hard part into winter. Shrinking weeks put the big amounts in summer, when his tips are best. He chose shrinking.
52 rows with each week’s amount, the total so far and small rewards at 10, 25, 50, 75 and 100 percent.
spread the missed money, save a double week once a month, or restart lower with a few more weeks. The message: adjust, do not quit.
its own savings account, a transfer on payday, and any surprise money added on top.
Andy liked the shrinking pattern for one reason: December would be his easiest month, not his hardest.
A year of saving, missed weeks included
First month · Autopilot – the transfer ran every Friday with his pay. A coworker got a weekly photo of the tracker, which made skipping harder.
Weeks 18 and 19 · The test – a cracked phone ate two weeks of savings. Instead of quitting, he added $13 to each of the next ten weeks and kept going.
Weekends · Extra cash – an old game console and an unused bike sold for $210. It all went into the car account.
Holidays · Small on purpose – his December amounts were the lowest of the year. Gifts got bought and the savings stayed whole.
Those two weeks were exactly where he quit the first time. This time they were just two rows in the table with a fix next to them.
Why this challenge worked when the first did not
Nothing in it required Andy to be perfect. The amounts followed his tips, the holidays were already planned in, and missed weeks had a clear fix. That is what got him from week 14 to the finish.
- A starting amount that feels easy
- Bigger weeks in your best months
- A transfer that happens by itself
- A plan for missed weeks
- A friend who sees your progress
- One chart for everyone
- The biggest weeks in December
- Savings mixed with spending money
- All or nothing thinking
- No one checking in
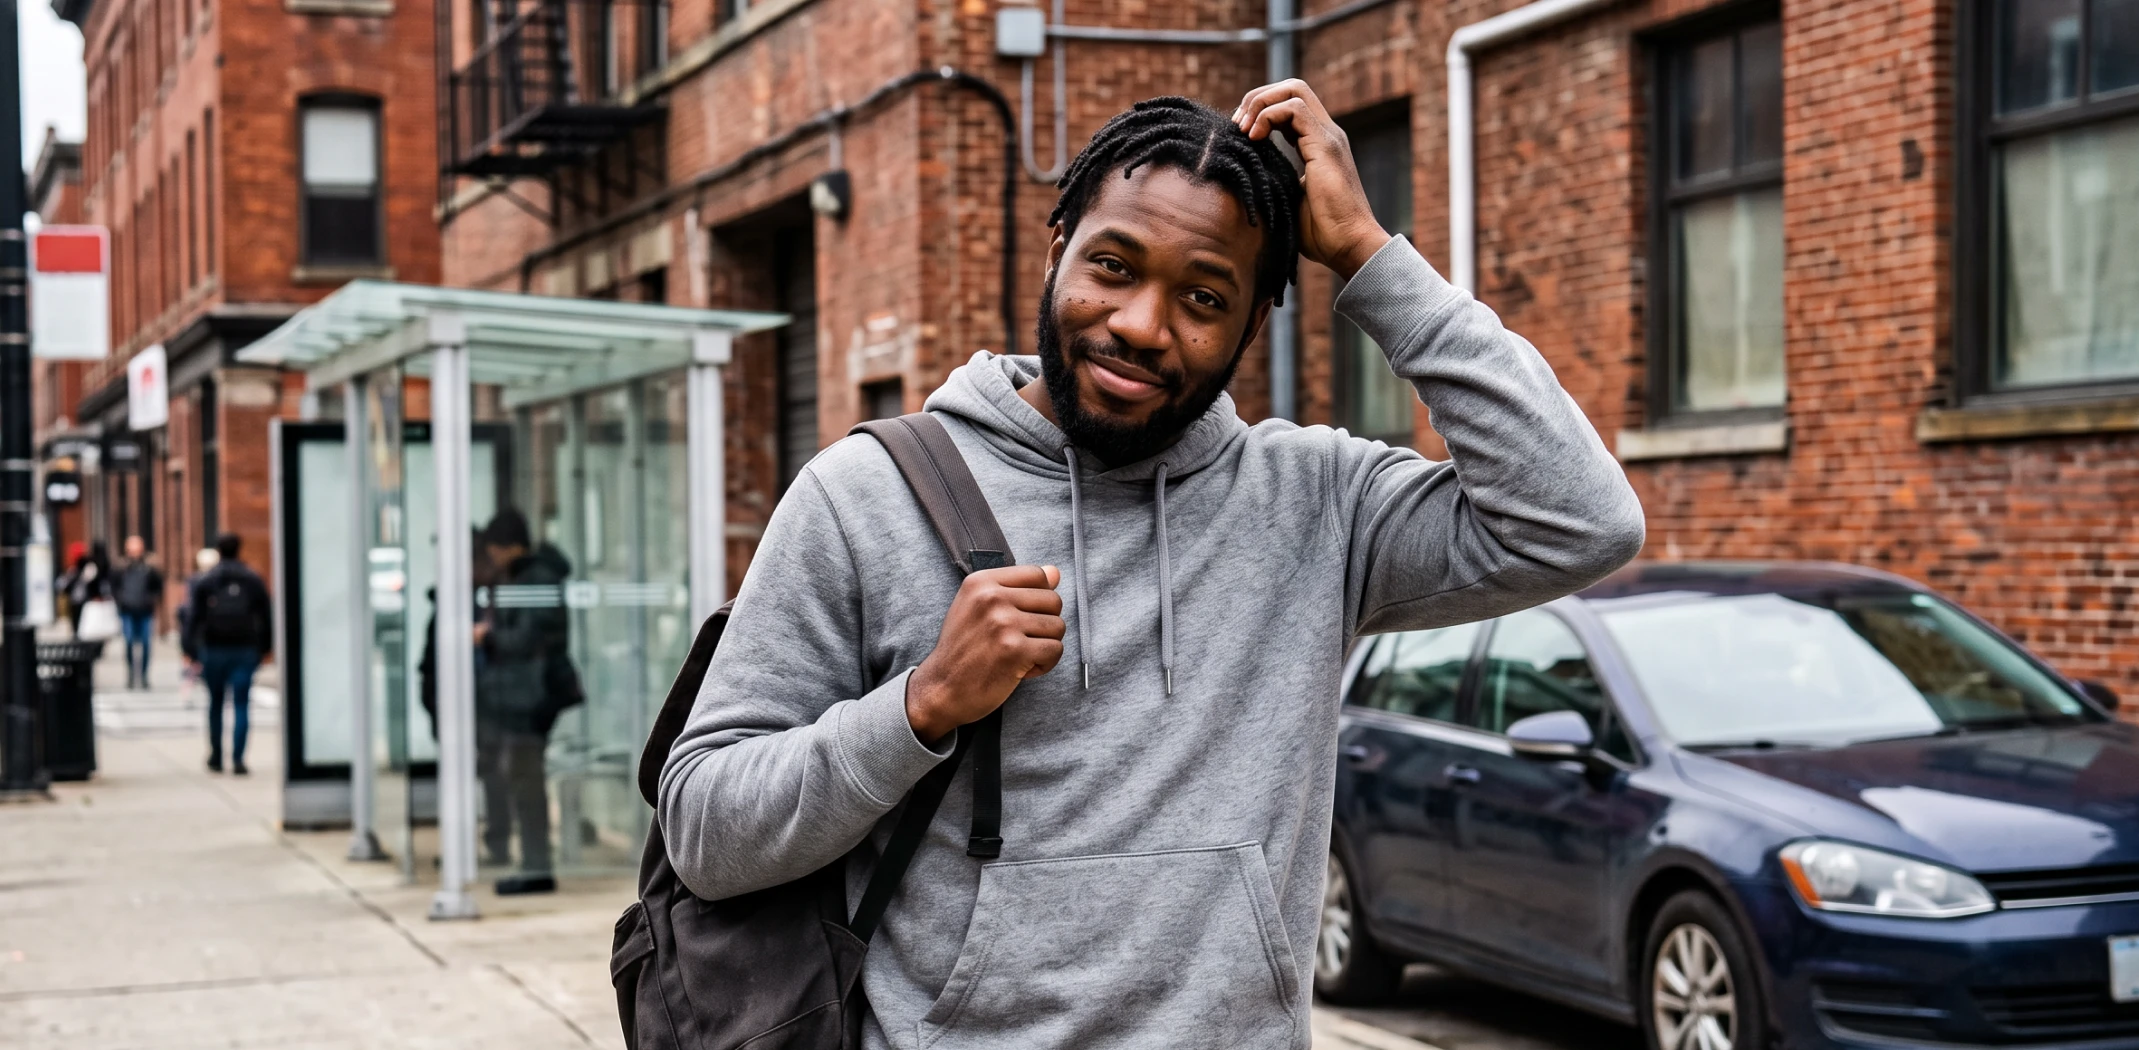
By week 46, with his tax refund added, Andy reached $3,000 and bought a used hatchback. Work is now a 20-minute drive, and late shifts end with him driving himself home.
How the choices compare
Andy looked at the usual ways people reach a goal like this.
| Choice | Price | Result |
|---|---|---|
| Free printable chart | Free | One pattern, no plan for bad weeks |
| Borrowing the full price | Years of interest | Car sooner, more paid in total |
| Paid saving app | Every month | Saves for you, ignores your busy months |
| 52-Week Savings Challenge Builder | $9 | A plan from your weekly amount, three patterns, catch-up options and a tracker |
“Do I have to start in January?” No. Week one is whatever week you start. Andy began in spring. What matters is that the expensive months in your year get smaller amounts, wherever they fall.
Others who made it to the last week
“School supplies in August used to wreck every plan I made. This one gave August the smallest amounts. Our beach trip, the first in four years, was paid for before we left.”
Vicky S. · school bus driver, Macon GA
“Five weeks behind, I was ready to stop. The restart option lowered my amount and added four weeks. Week 56 was my last one, and the goal was reached.”
Luke F. · grocery stocker, Fargo ND
Prefer saving that runs in the background? Try the Set & Forget Savings Plan. Results are different for everyone.
The best saving challenges are the ones you finish. Andy’s worked because it matched his tips, planned for December and had an answer for a bad week. Now the bus is just a memory.
CREATE MY OWN SAVINGS CHALLENGE
*Individual results may vary.