The same two suggestions turn up every January. Run a savings challenge, since watching a number climb keeps you at it. Or set an automatic transfer and stop thinking about it altogether, because willpower makes a poor plan. Both come from people who genuinely saved, both are given in good faith, and they disagree because each is describing a completely different kind of paycheck.
The quick answer
The honest framing is not “challenge or autopay” at all. One thing settles it: how alike your weeks are. A rising challenge demands its heaviest deposits at the finish, which for most households falls across the costliest months of the year. A flat transfer takes the identical sum every time and never picks a thin week to turn ambitious. Testing your thinnest week against the heaviest deposit settles it within minutes.
Coming up: the figure that decides this, a table you can find your own income in, and why so many challenges collapse in the same month every year.
The choice was never chart against autopay
Each side argues from its own experience. Somebody finished a challenge and remembers the momentum: the chart on the fridge, a week ticked off, the number climbing. Somebody else set a transfer running years ago and has not considered it since. Neither is mistaken about themselves, and neither is describing your paycheck.
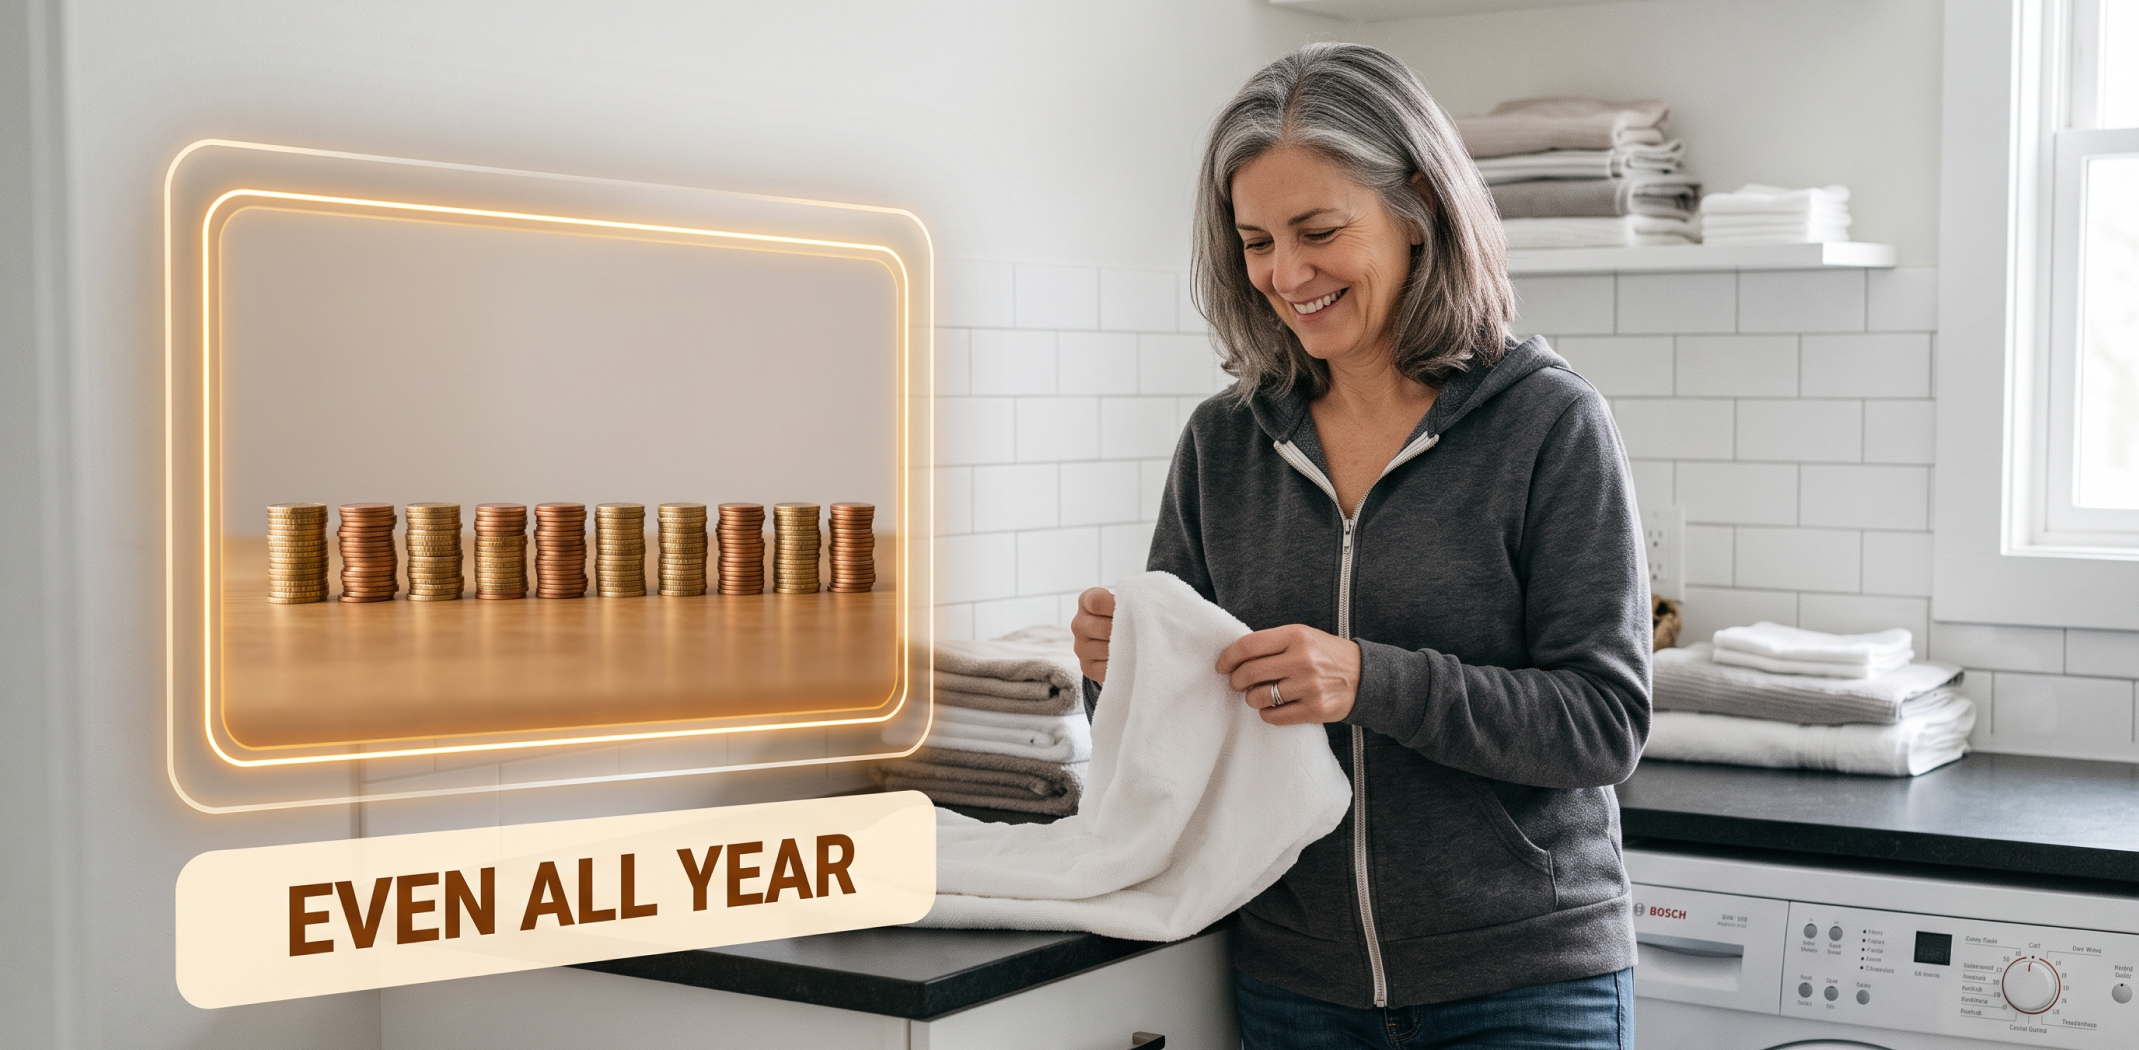
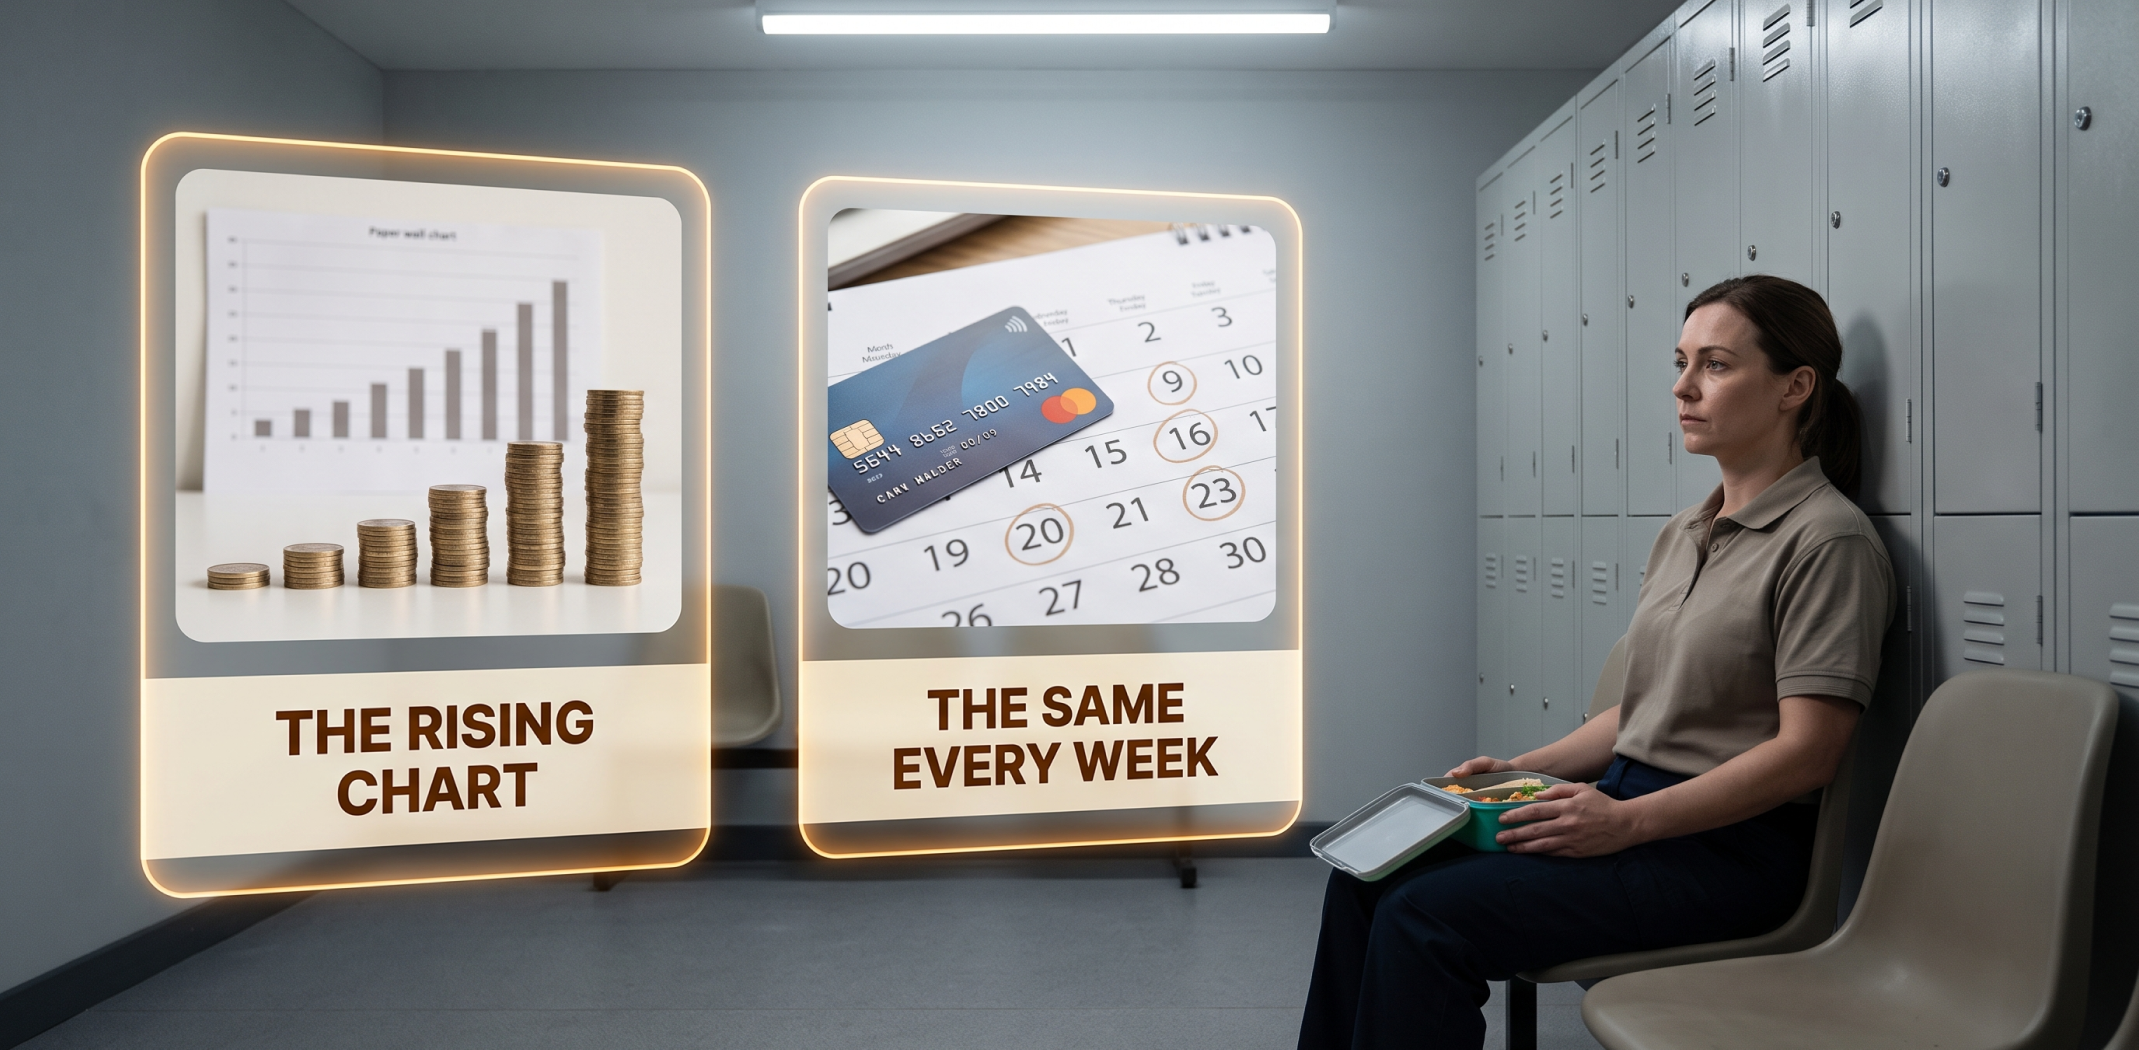
The mechanism deserves stating plainly. A classic rising challenge puts away a token sum in week one and its largest figures in the closing stretch, so the hardest deposits land across the final quarter – precisely when heating, gifts and short daylight are already pulling at that same account. A flat transfer spreads an identical total evenly and never demands more of December than of March. Laying both schedules against your own year is usually the moment the argument ends.
Which means the question was never which method carries more discipline. It is whether the largest week of the plan sits below what a thin week can actually spare.
Find your own income in the table
Establish what a thin week genuinely looks like for you, not an average one, then locate yourself in the table below. Sizing the worst week first takes a few minutes and tends to end the debate on the spot.
| Your income | What usually works | Why |
|---|---|---|
| Identical every week | A flat transfer generally wins | Nothing to decide and nothing to skip |
| Steady, with a tight season | A flat transfer, or a challenge that peaks early | The rising version breaks in your tight months |
| Tips, shifts or commission | A challenge fitted to your own weeks | The amount can flex whenever a week runs thin |
| Not sure what a bad week looks like | Work that out first | Every row above depends on it |
Treat those as a starting point rather than a rule. Whether you are paid weekly or monthly, when your bills fall and how much sits in the account before payday all move the line, which is exactly why the answer is yours rather than general.
With a challenge, shape beats total every time
This is the part most people miss: the total at the finish is the dullest number in any savings challenge, since nearly every version arrives in roughly the same place. What differs is when it asks for the money, and reordering the weeks to fit your year is what turns an abandoned chart into a finished one.
Three adjustments usually separate finishing from quitting.
Identical total · three ways to survive it
Front-load it, or run it backwards. Place the heaviest deposits in your easiest months and the lightest in the tightest ones. The total does not change and the breaking point simply vanishes.
Match the rhythm to your payday. Weekly deposits on a monthly salary means three weeks of waiting and one of scrambling. Fortnightly and monthly versions exist for a reason.
Allow yourself to skip, deliberately. A plan carrying two permitted misses survives a rough month. One with none gets abandoned the first time life intervenes, and that is a flaw in the design rather than in you.
The same money waits at the end. Order and rhythm decide whether you ever reach it.
Notice that none of this asks for more discipline than you already have. It asks for a schedule that was built around your year rather than around a chart somebody printed in January.
Why so many collapse in the same month
Because the classic version was designed to look tidy rather than to be completed. Rising deposits produce a handsome chart while loading maximum pressure onto the weeks with the least room. Somewhere around week forty the deposits stop resembling a game, one gets missed, the streak breaks, and it is the broken streak people walk away from rather than the saving.
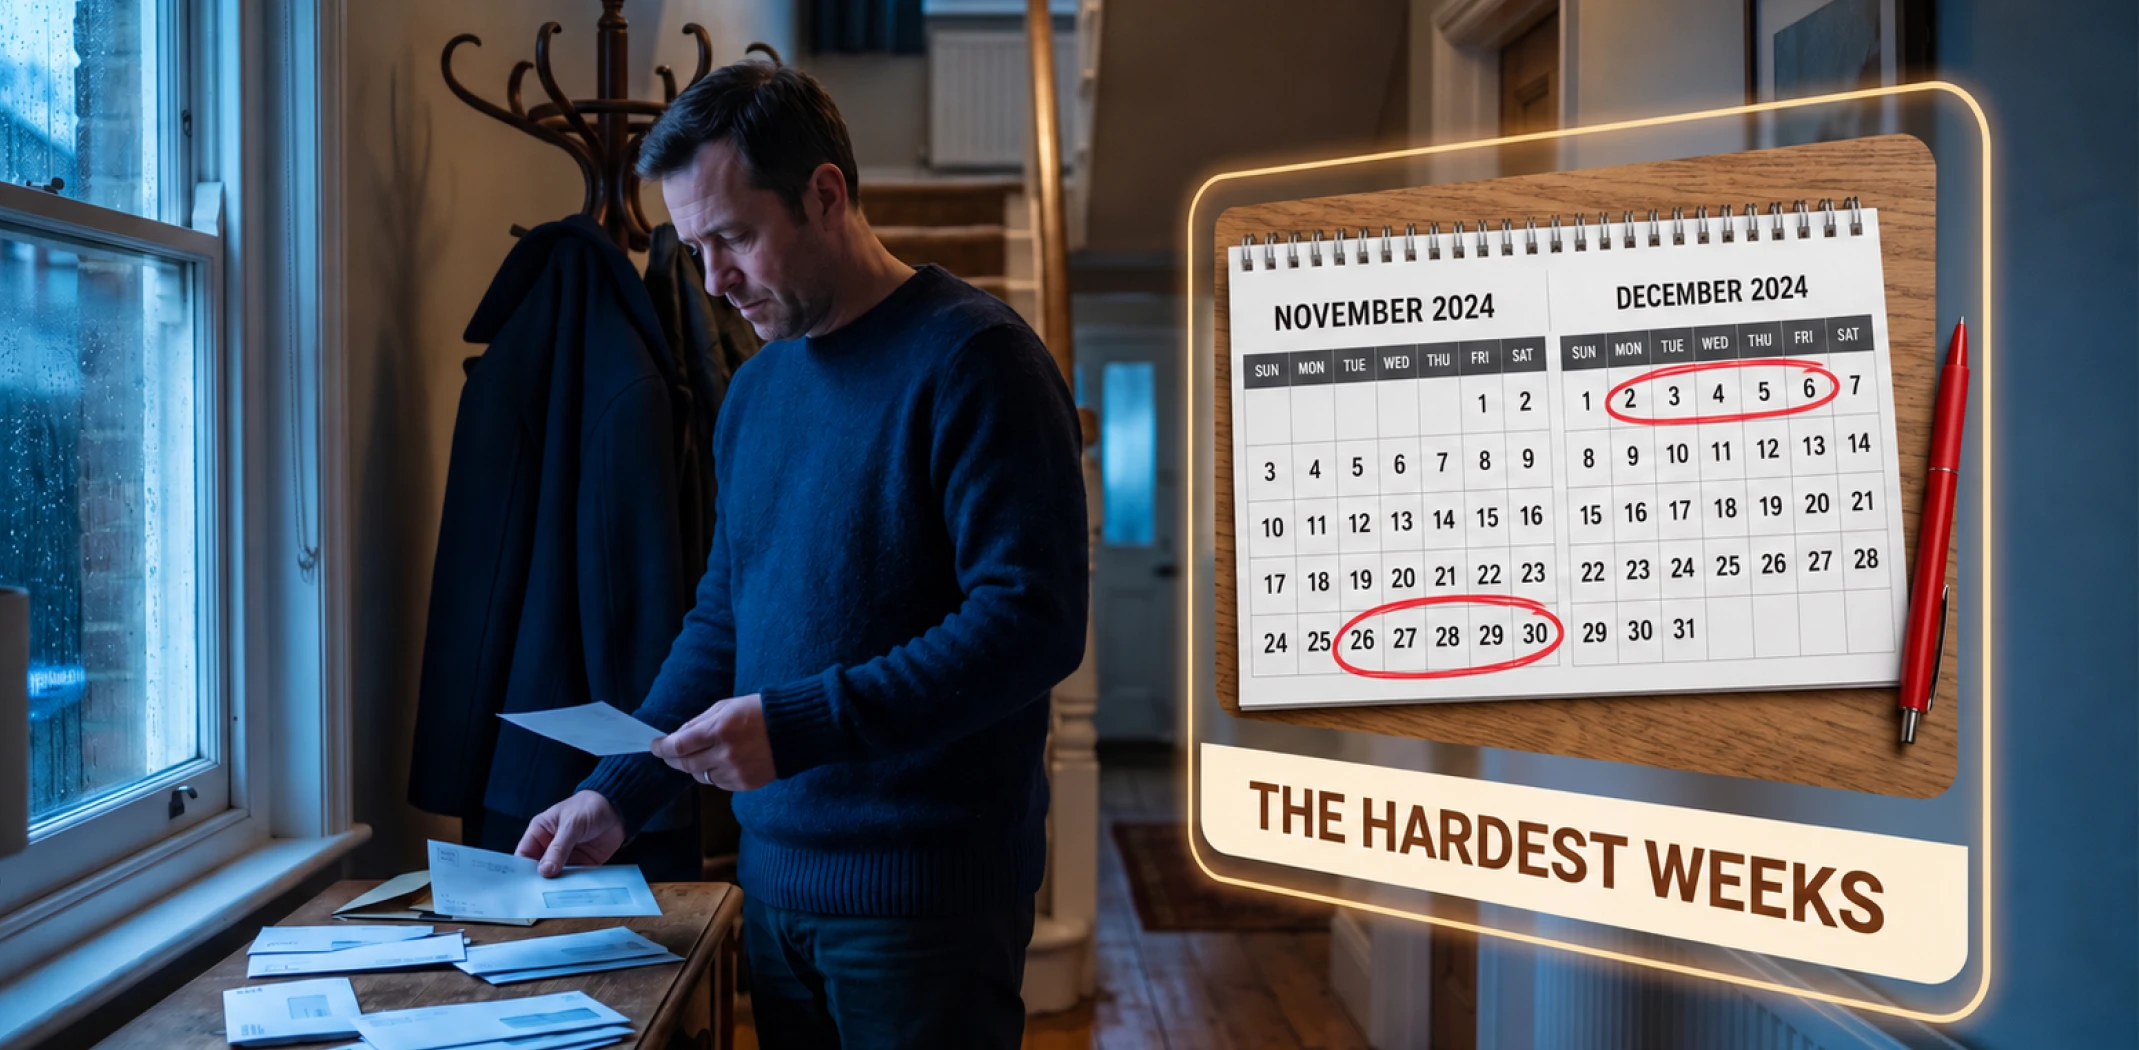
The opposite error is quieter. A flat transfer pitched at an optimistic figure fails another way entirely: it leaves on schedule, the account runs dry by the twentieth, and the money comes straight back out a week later. That is not saving, it is a round trip. Setting the amount from a poor week rather than a good one is what stops it. Results vary and this is general guidance.
Printed chart vs guesswork vs a fitted plan
You can build either version yourself, for free, on a piece of paper. Here is how the usual routes compare with shaping the schedule around your own income.
| Way to decide | Cost | Built on your weeks? | Time |
|---|---|---|---|
| Print a standard chart | Free | No – the same weeks for everyone | Abandoned around week 40 |
| Set a transfer and hope | Free | No – the amount is a guess | Ongoing |
| A budgeting app | $5–15/mo | Sometimes – still needs the figure from you | Ongoing |
| 52-Week Savings Challenge Builder | $9 | Yes – your weeks, your rhythm, your skips | About 15 min |
“Is the whole thing not a gimmick?” The chart is a gimmick; the psychology behind it is not. Visible progress genuinely helps people who have failed at saving quietly, which is most people who try. What deserves the criticism is the standard schedule, not the idea: it asks the most of you in the months that have the least, then treats the resulting miss as a personal failing. A schedule built around your own year keeps the part that works. This is general educational guidance about household saving rather than financial advice.
If that still sounds like a minor detail, two people ran identical totals and only one reached the end.
Two people, two unrecognisable weeks
One of them is paid the same figure every Friday. The other has never had two matching weeks in her life.
“I tried the printed chart twice and stopped both times in November. The third year I just set the same amount every week and forgot about it. Boring beat clever by a distance.”
Dane P. · council groundskeeper, Spokane WA
“A fixed transfer bounced twice in my first month because my weeks are nothing alike. What worked was a challenge I could flex, with the big weeks in summer when the tips are good. Same total, finished for the first time.”
Colette M. · bartender, Lubbock TX
If the income itself is the unpredictable part rather than the schedule, the Irregular Income Budget Plan is built for budgeting against a month you cannot forecast. Results vary; this is general guidance rather than financial advice.
Five short answers, and a schedule fitted to your own year lands the same day, with the heaviest deposits shifted into the months that can carry them. Everything is built from what a thin week genuinely looks like for you rather than from a chart printed for everyone at once, which is precisely why it tends to outlast the printed versions. Two skips come built in, deliberately.
*Individual results may vary.