Every article says diversify, and the reasoning holds up: a single income is a single point of failure. So a second thing begins, then a third, and eighteen months on there are three half-finished projects while the main income has quietly stopped growing because nobody was minding it. The advice was not wrong. It was simply missing the part about timing, which is what a read on your own income first supplies.
The quick answer
The honest framing is not “one income or several” at all. One thing settles it: whether your main income is still rising. For as long as it is, deepening generally beats starting afresh, since you are adding to something already proven. Once it levels off, or where it rests on one client or employer, the second stream stops being a distraction and becomes insurance. Checking which of those two you are in takes minutes.
Coming up: the thing that decides this, a table you can find your own situation in, and the two opposing risks that keep the argument alive.
The choice was never focus against spreading out
Each side is describing a genuine disaster. Somebody lost the single client that made up most of their income and will tell you never to lean on one thing again. Somebody else spread across four projects, handled all of them adequately and none of them properly, and will tell you focus is the whole game. Both learned something true, and neither is describing the state your income is currently in – which is why starting from your own two years settles it faster than either story.
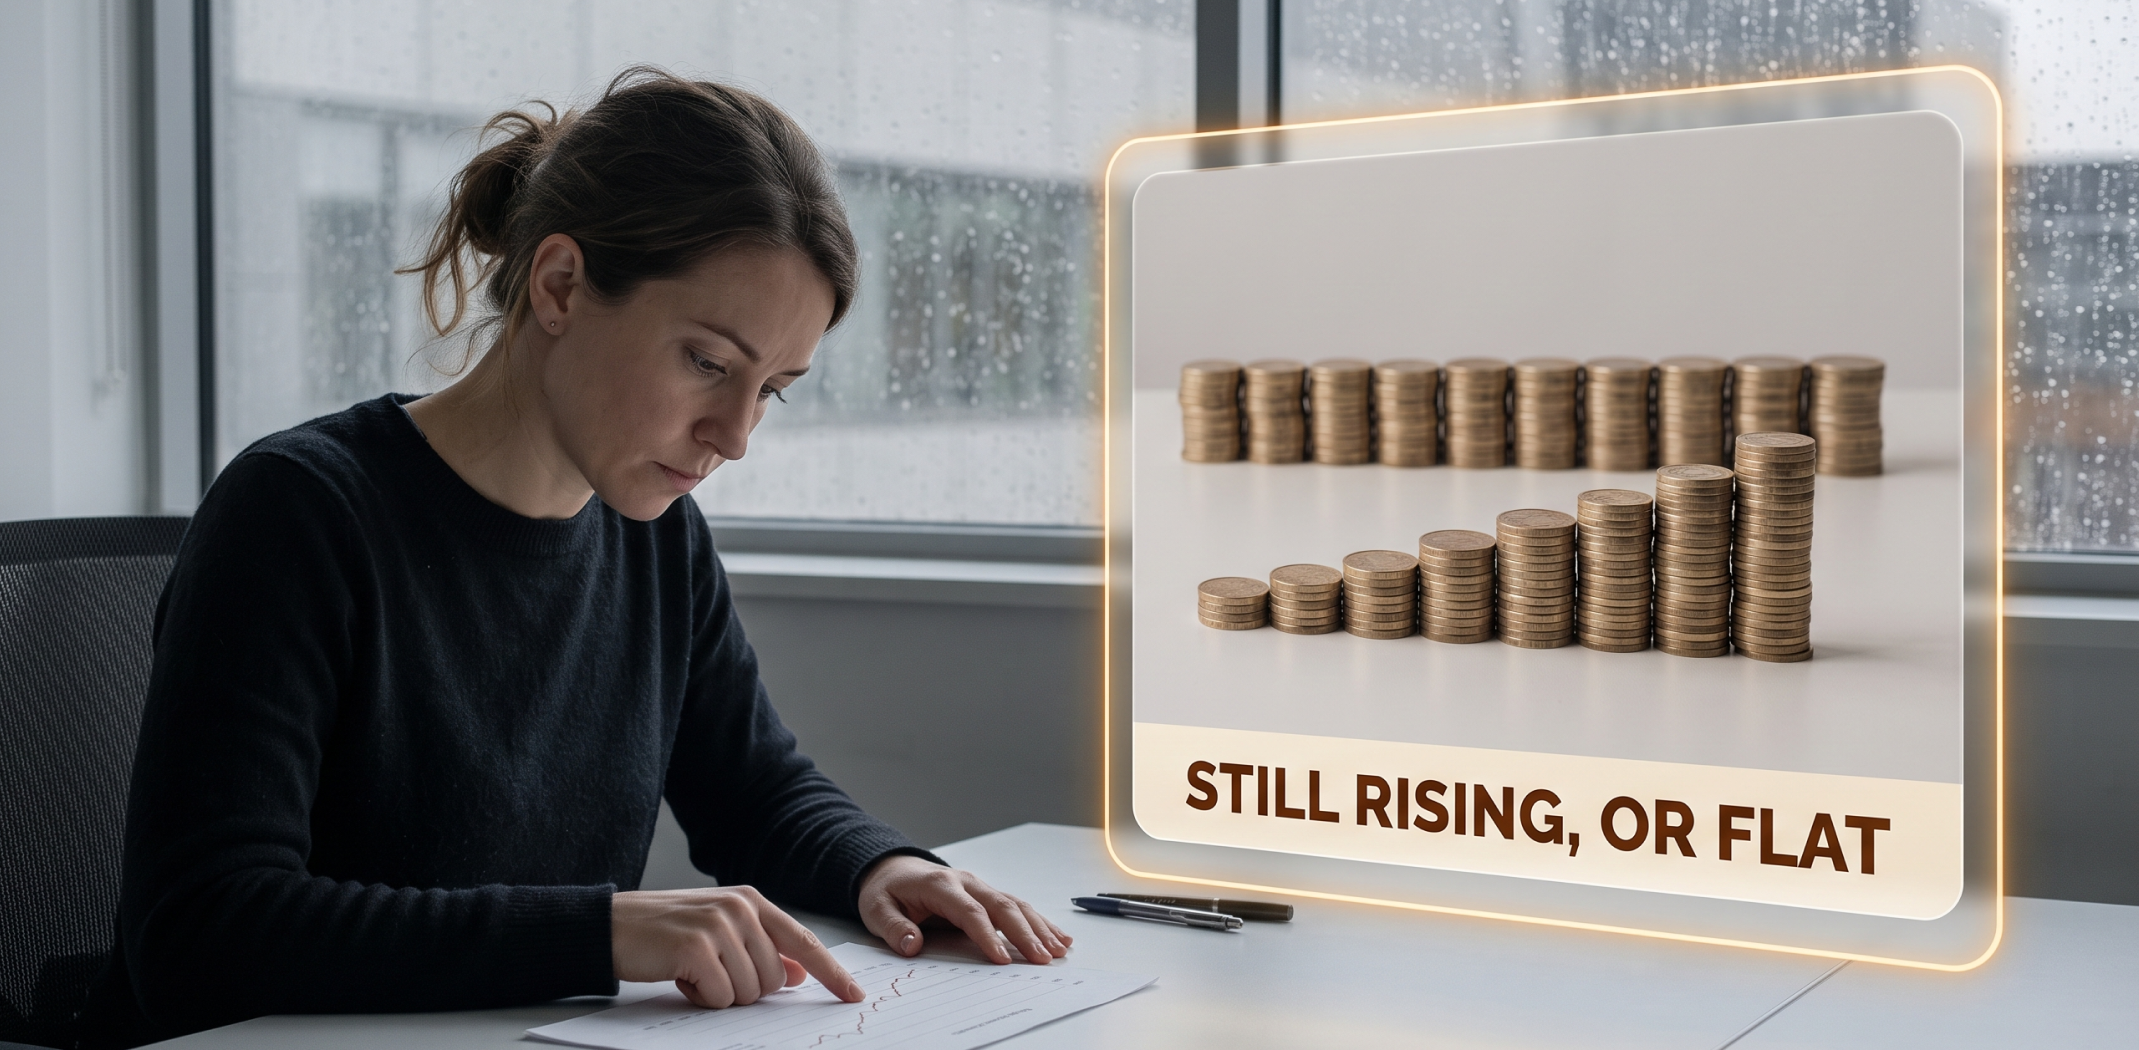
The mechanism deserves setting out. Two opposing risks sit here, and hardly anybody weighs them together. Concentration risk means losing the lot at once when a single source vanishes. Dilution risk means two half-finished streams together earning less than one completed one, because most income takes a while before it repays the effort. Weighing both risks against your own income is what turns this from a debate into a decision.
Which means the question was never whether spreading out is wise in principle. It is which of the two risks is larger for you right now, and that shifts as your main income shifts.
Find your main income in the table
Examine what your main income has done across the past two years and how many places it arrives from, then locate yourself in the table below. Sorting that honestly takes a few minutes and usually settles the timing question.
| Your main income | What usually works | Why |
|---|---|---|
| Still rising, several clients | Deepen it and wait | Adding now dilutes something that already works |
| Still climbing, one client or employer | Add a small second stream | The growth is real and so is the single point of failure |
| Level for a year or longer | Add, and choose it deliberately | Deepening has stopped paying, and that is the signal |
| Falling, or a contract ending soon | Add quickly, and defend the main one | This is precisely the situation the advice was written for |
Take those as a starting point, not a rule. How replaceable the main income would be, how much warning you would get, whether the field is shrinking and how many hours you genuinely have all move the line, which is why the answer belongs to your situation.
If you are adding, add exactly one
This is the part most people miss: the way diversifying fails is almost never picking the wrong stream. It is picking three simultaneously. Each new source has a stretch at the beginning where it costs hours and returns nothing, and running three of those simultaneously is how eighteen months disappear. Sequencing them instead of stacking them is the whole difference.
A second stream that lasts tends to carry three properties.
Worth starting · three tests it must pass
It fails for reasons the first does not. A second client in the same industry is not diversification at all. Where one downturn removes both, you have doubled the work and kept every bit of the risk.
It runs on something you already hold. A skill, a tool, an audience, a set of contacts. Beginning from nothing is precisely what stretches the unpaid phase long enough to walk away from.
It carries a size and an end date. Three months, or twenty hours, agreed before starting. Lacking that, a stream that is going nowhere quietly keeps consuming the time the main income needed.
A different failure, assets you already hold, a bounded test. One at a time, and the next only once this one stands on its own.
Notice that none of this argues against having several incomes eventually. It argues about order, and a plan that builds them in sequence exists so the first one is finished before the second one starts.
The real price of adding too soon
It costs you the main income. Attention is what grows any established source, and it happens to be the one input you cannot buy more of. Remove a third of it during the years the first income was still compounding and you have swapped a known return for an unknown one.
The opposite error hits harder when it arrives, which is why the advice exists in the first place. A single client or employer vanishing removes the entire income at once and seldom gives warning. So: check whether your main income is still growing, count how many places it comes from, then either deepen it or add one thing deliberately. A plan that names which risk you are carrying is what makes that a decision rather than a reflex.
Focusing vs stacking vs sequencing
You can work this out yourself, for free, with two years of records and an evening. Here is how the usual approaches compare with sequencing streams deliberately.
| Way to decide | Cost | Built on your own risk? | Time |
|---|---|---|---|
| Focus and hope | Free | No – ignores concentration risk | Fine until it is not |
| Start three things at once | Free | No – three unpaid stretches at once | Usually abandoned |
| A business coach | $100–250/hr | Sometimes – costly before the second stream earns | Ongoing |
| Income Diversification Planner | $39 | Yes – your risk, your assets, one at a time | About 15 min |
“Is waiting not simply an excuse not to begin?” Sometimes it genuinely is, and that deserves saying outright rather than letting timing become a permanent reason for inaction. The difference is whether you can name the condition that would change your answer. “When my main income stops growing” or “when this contract ends” is a plan. “When things settle down” is a way of never starting, and a year from now the situation will look identical. This is general educational guidance rather than business or financial advice, and outcomes vary considerably with your field and effort.
If that still sounds like hedging, two people met the same choice from opposite ends.
Two people, two opposite mistakes
One of them added four things while the first was still climbing. The other refused to add anything until the decision was taken out of his hands.
“Four projects in a year, all of them at the beginning stage, and my actual income fell because nobody was looking after it. Finishing one before starting the next was the only thing that changed.”
Solveig R. · translator, Fort Collins CO
“One builder was almost everything I earned and I kept saying I would sort it out after the busy season. The busy season ended when they did, and I would rather have started the second thing while I still had a choice.”
Boniface A. · cabinet installer, Erie PA
Several income sources arriving on different schedules makes a month harder to predict, and the Irregular Income Budget Plan is built for exactly that. Results vary; this is general guidance rather than business or financial advice.
Five short answers, and a read on your own situation lands the same day: whether the main income is still climbing, how exposed it sits to one client or employer, and which of the two risks currently weighs more. Where the answer is to add, it arrives as a single stream rather than four, assembled from what you already hold and carrying an end date on the test. Order is the part deciding whether any of it lasts.
*Individual results may vary.