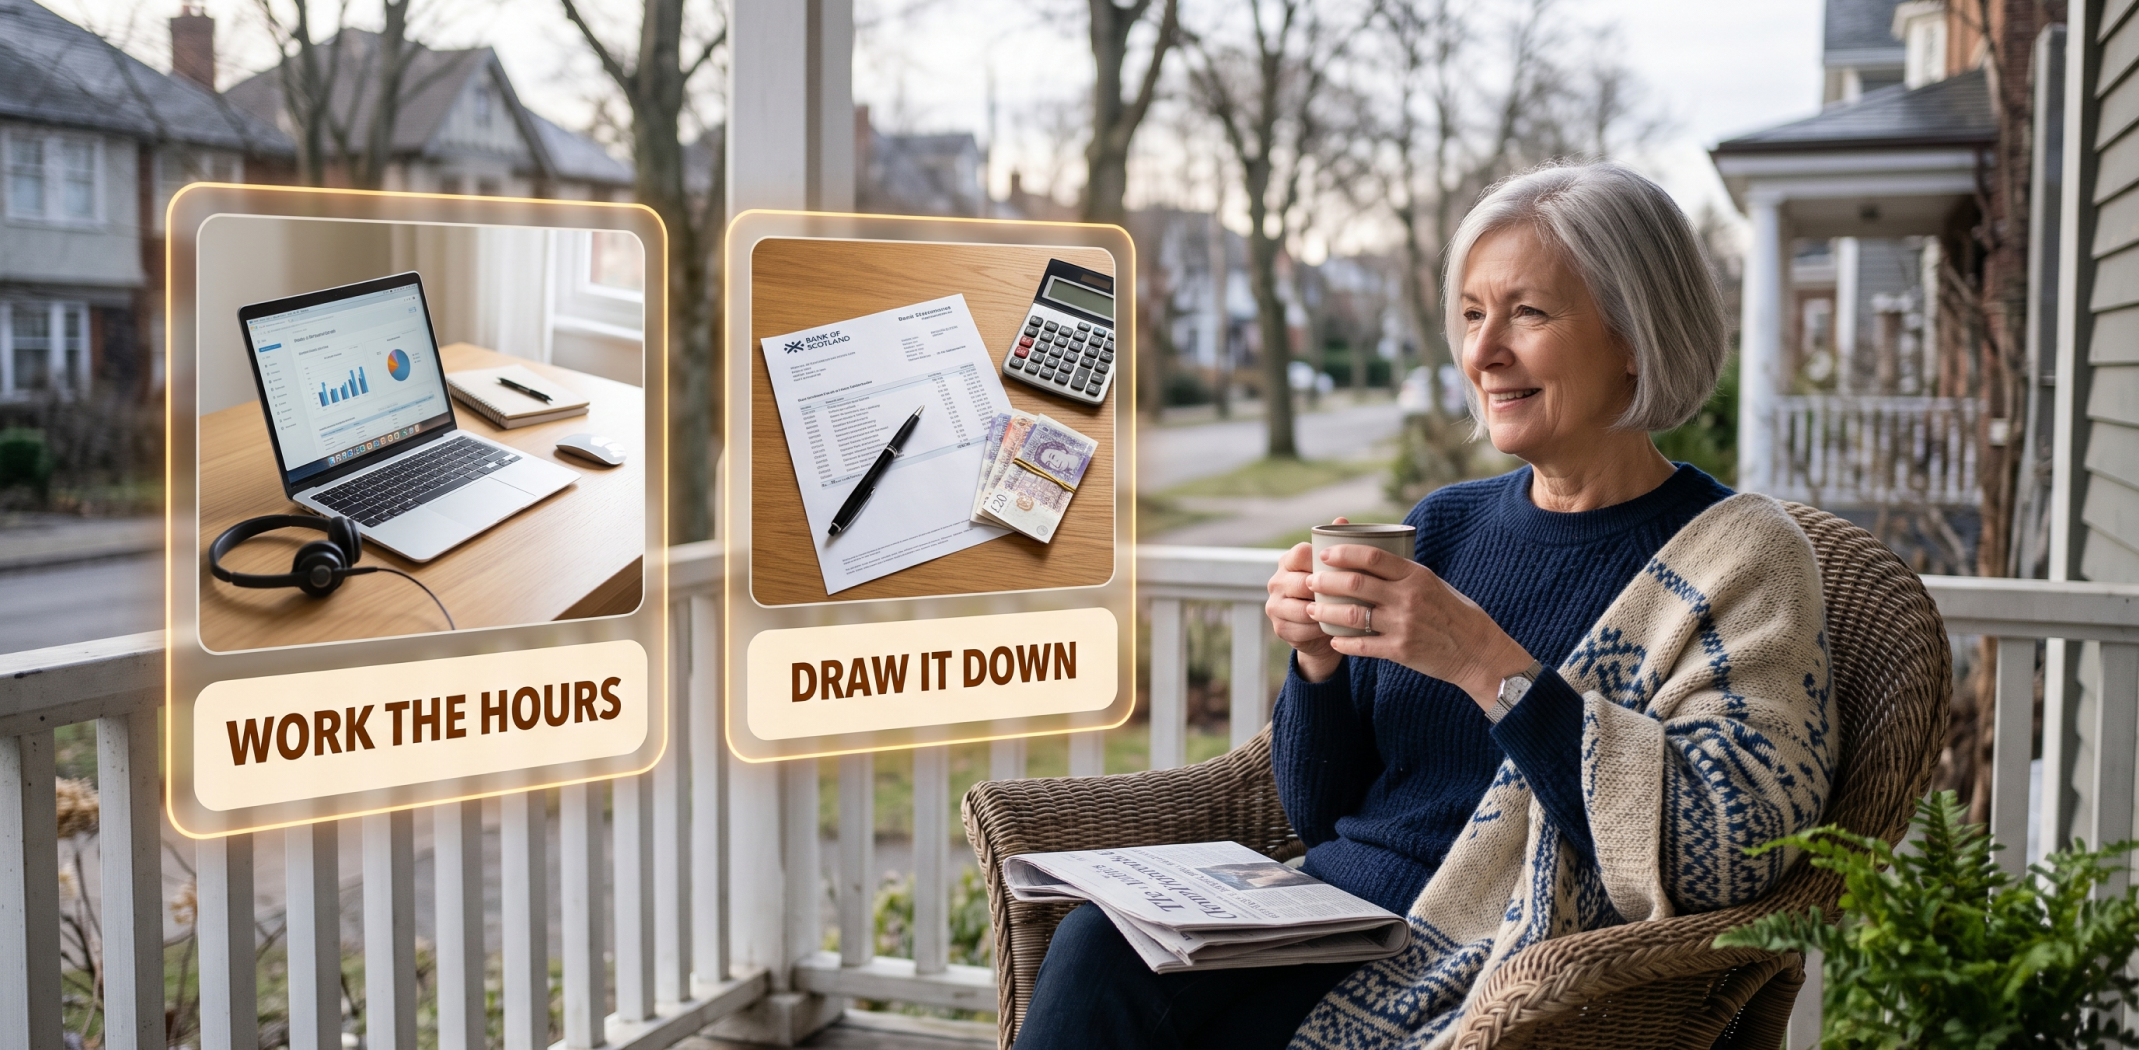
The pension lands, the sums get checked, and a gap appears. Nothing alarming – a few hundred a month. Two obvious ways to close it: draw a little more from what was saved, or put in a small number of hours. Most households drift between the two for a year, quietly taking extra while intending to look for something, which is the single option nobody ever wrote a plan for.
The quick answer
The honest framing is not “work or withdraw” at all. One comparison settles it: the size of the monthly gap set against what you have saved. A modest gap closed with a few hours costs you some mornings. That same gap drawn from a portfolio month after month for decades costs a great deal more than the sum involved. Sizing the gap before you choose takes minutes. Outcomes depend on markets and circumstances, and this is general education rather than advice.
Coming up: the figure that settles this, a table you can find your own gap in, and why a handful of hours achieves more than the pay rate suggests.
The choice was never work against withdraw
Both positions come with feeling attached. One insists you did not save for four decades in order to return to work. The other points out that every dollar left invested is a dollar still doing something. Each is true, neither is a calculation, and that is precisely why the decision keeps sliding by another month of quietly taking extra.
The mechanism runs like this. A few hours of work achieves two things simultaneously: money comes in, and the same amount stays in your savings, where it may carry on growing for the remainder of your retirement. A withdrawal does the reverse, twice over. That is why a modest number of hours moves the picture more than the hourly rate suggests, and seeing both effects totalled is usually the moment the argument ends. Nothing is guaranteed and markets vary.
Which means the question was never which choice carries more dignity. It is how large the gap sits relative to what you hold, and how many hours would genuinely be needed to close it.
Find your own gap in the table
Establish the shortfall between what arrives each month and what a month genuinely costs you, then locate that figure in the table below. Sorting the gap into a band takes a few minutes and usually ends the debate on the spot.
| Your situation | What usually wins | Why |
|---|---|---|
| Small gap, healthy savings | Draw it and stop worrying | At that scale the withdrawal barely registers on the plan |
| Small gap, thin savings | A few hours usually wins | Small hours, large effect on how long it lasts |
| Large gap, thin savings | Hours, and revisit the spending too | Withdrawals of that size shorten the runway noticeably |
| Gap unknown | Work it out this week | Every row above depends on it |
Take these as a starting point, not a rule. Health, whether the pension rises with prices, how the money is invested and what earning affects where you live all shift the line, which is exactly why the answer belongs to you rather than to an article.
Why a handful of hours goes so far
This is the part most people miss: the comparison is not an hourly wage against a withdrawal of matching size. It is an hourly wage against a withdrawal plus whatever that money might have earned across the rest of your retirement. Putting the two side by side is what makes twelve hours a week look different than it did.
Where hours are the answer, their shape matters far more than the rate.
Which hours are worth taking · and which are not
Name the hours first, not the role. Decide on twelve hours a week before opening a single listing, and let that do the filtering. Plenty of adverts are written to sound flexible without being so.
Check the actual schedule, not the headline. Part-time often means fixed shifts or on-call cover, and who picks when those hours fall matters more than how many there are.
Refuse anything with a fee to start. Legitimate work does not ask you to pay for a kit, a course or a background check up front. That rule alone removes most of what targets retirees.
Check what the income touches. Earning can affect tax, benefits or a pension depending on where you live and your age. Confirm it with the relevant agency before you accept anything.
Four checks, in that sequence. Hours come first because everything else can be negotiated and that cannot.
Notice that none of this requires taking a job you dislike. It requires stating the hours out loud, and a shortlist filtered by hours first is what stops the search from turning into four hundred listings.
The price of another year of drifting
It costs both options simultaneously. Drawing a little extra each month without deciding amounts to a withdrawal plan nobody committed to paper, and it grows without anyone noticing. Meanwhile no search ever begins, so a year goes by with the gap still open and the savings thinner than any spreadsheet predicted.
The opposite error is equally real. Accepting work before sizing the gap usually means putting in more hours than the shortfall ever demanded, which is how people come to resent a job they never needed. So: size the gap, check what the hours would cover, then choose deliberately. A plan built around your own hours is a planning tool, not advice – results vary.
Drifting vs drawing vs working it out
You can settle this yourself, for free, with a statement and an afternoon. Here is how the usual routes compare with sizing the gap and filtering by hours.
| Way to decide | Cost | Built on your gap? | Time |
|---|---|---|---|
| Take a little extra each month | Free | No – a plan nobody wrote | Ongoing |
| Scroll job boards for months | Free | No – sorted by role, not hours | Weeks of reading |
| A financial adviser | $150–300/hr | Sometimes – costly for one question | Ongoing |
| Senior Remote Job Finder | $11.99 | Yes – your gap, your hours, a shortlist | About 15 min |
“Should I not simply enjoy the retirement I paid for?” You should, and that is exactly the case for sizing the gap instead of drifting. Drawing more without a plan is not enjoying retirement; it is postponing a decision, and the postponement is the part that shortens the runway. If the numbers say draw it, draw it with confidence. What the figures buy you is the confidence, not the obligation to work. Rules on tax, benefits and pensions differ by country and age, so check your own position with the relevant agency or a licensed professional.
If that still sounds abstract, two people met the same gap and chose opposite ways.
Two people, two opposite answers
One of them held savings deep enough to make the question academic. The other had a gap that a few hours closed entirely.
“I was taking an extra three hundred a month and pretending that was a decision. Written down, twelve hours a week covered it and left the money where it was. I work two mornings and the plan stopped shrinking.”
Estelle H. · retired ward clerk, Missoula MT
“I had convinced myself I needed to go back to work out of duty. The figures said my gap was small enough that drawing it changed almost nothing. Knowing that was worth more than the job would have been.”
Warren K. · former dispatch supervisor, Amarillo TX
If the worry is less about this month and more about whether the money lasts the whole way, the Retirement Income 30-Year Plan is built for that horizon. Results vary; this is general guidance, not financial, tax or benefits advice.
Five short answers, and your monthly gap lands the same day alongside the hours that would close it. Everything is worked from your own pension, savings and spending rather than from a rule about what retirees ought to earn, so whichever way it falls the reasoning is yours to see. The figure is usually smaller than people expect.
*Individual results may vary.